
2026-04-11 · auto, claims
Updated: 2026-10-04
By InsuraFAQ Editorial Team · Reviewed for accuracy
Auto Claims Step-by-Step
After a crash, take care of people and immediate safety before you think about paperwork. Once you are safe, preserve the basic details and use your own policy and insurer’s instructions to decide what to report. The National Association of Insurance Commissioners (NAIC) notes that auto insurance rules and required coverage vary by state, so your policy and state rules control the details. Read NAIC’s auto-insurance consumer guide.
Right after a crash: safety first, then your claim file
- Get urgent help first. If anyone may be injured or the scene is unsafe, call emergency services and follow instructions from responders. Do not put yourself in traffic or attempt to move a vehicle unless it is safe and permitted.
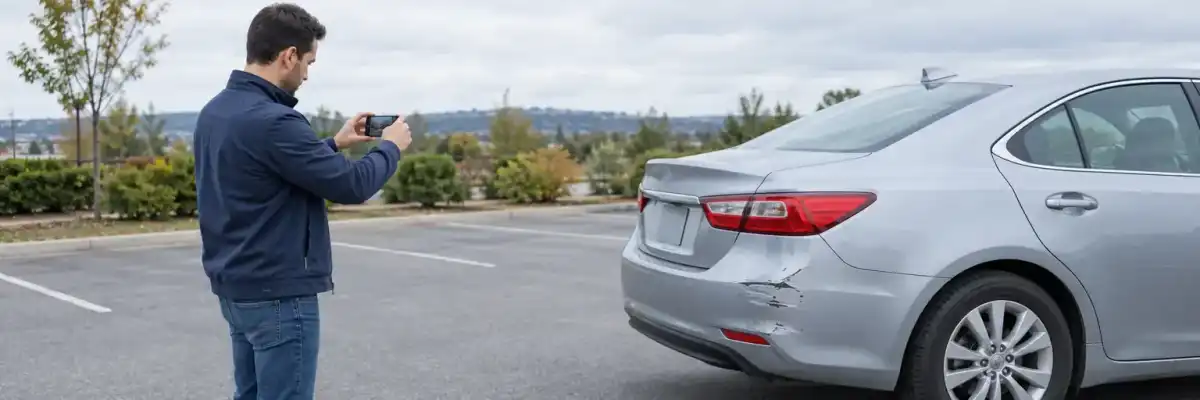
- Exchange and record the basics when it is safe. Note the other driver’s contact and insurance information, vehicle details, location, time, and any witnesses. Take photos of the scene and damage if you can do so safely.
- Check your policy and contact the right insurer. Your declarations page and policy explain your coverages and deductible; your insurer can tell you its reporting process and what information it needs. Reporting duties and deadlines can differ by policy and state, so do not assume one carrier’s timeline applies to another.
- Keep a simple record. Save claim numbers, photos, receipts, estimates, and notes from calls. Ask the insurer what happens next and whether it needs an inspection, additional documents, or repair information.
For a high-level overview of common auto coverages and state variation, see NAIC’s consumer guide. If you are unsure whether a loss is covered or when to report it, ask your insurer rather than relying on a generic timeline.
Steps to file a claim
- Start with safety, then document what you can: photos, respondent or police-report details if one is made, and witness information can help you give the insurer a clear account.
- Report through your insurer’s stated channel: use the app, website, or claims phone number identified by your carrier, and ask what timing and documentation apply to your policy.
- Follow the inspection process your insurer provides: it may request photos, an estimate, or an inspection before it evaluates covered damage.
- Review repair and payment details before authorizing work: confirm the deductible, estimate, coverage decision, and any repair-process requirements with the insurer and shop.
- Keep the final claim record: review communications and payment information, and retain receipts and other claim documents.
Common pitfalls
- Waiting to notify your insurer without checking its reporting instructions can complicate the claim.
- Missing photos or receipts can make it harder to document the loss or expenses.
- Assuming your deductible, limits, or coverage apply without reading the policy can lead to surprises.
What to document at the scene
When it is safe to do so, review your coverage and follow any instructions from responders. Your declarations page identifies listed limits and deductibles; the full policy controls whether a particular loss or expense is covered. Then document the scene as safely as you can:
- License plate, make, model, and color of every vehicle involved.
- Driver’s license and insurance card of the other driver(s). Photograph both sides.
- Police report number and the responding officer’s name and badge, if a report was filed.
- Wide-angle scene photos showing vehicle positions, skid marks, traffic signals, and road conditions.
- Close-up photos of visible damage from multiple angles, without entering traffic or an unsafe area.
- Names and phone numbers of witnesses. Brief written statements if they are willing.
- Time, weather, and a short written description of what happened while it is fresh.
What to say (and not say) to adjusters
- State the facts: time, location, direction of travel, and what you observed. That’s it.
- Do not speculate about fault, speed, or who was “mostly” responsible. Adjusters record these calls.
- Do not accept a recorded statement from the other driver’s insurer without first consulting your own adjuster or an attorney.
- Do not sign a release or cash a settlement check until you have a written repair estimate and a medical evaluation if anyone was injured.
- Ask for the claim number, adjuster’s name, direct phone, and email at the start of every call, and keep a running log of each conversation.
How to handle a total loss disagreement
- Request the carrier’s valuation report in writing. It should list comparable vehicles (comps) used to set the actual cash value.
- Check each comp against your vehicle’s trim, mileage, condition, and recent upgrades. Adjusters sometimes use lower-trim comps.
- Submit your own comps from local listings (same trim, similar mileage, same region) and request a revaluation.
- Ask how sales tax, title, registration, and any recent pre-loss repairs are being handled in the settlement.
- If you owe more than the settlement, see gap insurance. For the broader process, see coverage for totaled cars.
- If negotiation stalls, you can invoke the appraisal clause (if your policy has one) or escalate through your state Department of Insurance.
When to escalate
- The claim is denied and you believe a covered loss occurred. See claims denial appeals for the formal process.
- The adjuster is unresponsive after you have followed the insurer’s stated contact or escalation process.
- Repair shop findings contradict the adjuster’s estimate and the carrier will not reinspect.
- You cannot resolve a documented disagreement about covered damage or valuation after using the insurer’s review process.
- If the at-fault driver is uninsured or underinsured, your own uninsured motorist coverage may be the primary path to recovery.
- Injuries, disputed fault, or potential legal deadlines make the claim more complex; consider qualified legal advice rather than relying on this general guide.
- State escalation paths: your state Department of Insurance complaint process, small claims court for amounts below the state limit, or a licensed public adjuster or attorney for complex cases.
Frequently asked questions
How long do I have to file an auto insurance claim?
Most policies require “prompt” notice or notice “as soon as practicable” rather than a specific number of days, so check your declarations page and your carrier’s stated reporting window. Delaying the claim can slow payment and weaken your documentation, so notify your insurer as soon as you are safe and have the basic facts.
Should I file a claim or pay out of pocket?
Compare the realistic repair cost to your deductible: if the bill is only modestly above the deductible, paying out of pocket may net out similarly once you account for the long-run premium impact of a claim on your record. If injuries, multiple vehicles, or disputed fault are involved, file the claim — the protections of the policy outweigh the premium effect.
What if the other driver does not have insurance?
If the at-fault driver is uninsured or underinsured, your own uninsured motorist coverage is typically the primary path to recovery. Open the claim with your own carrier, document the other driver’s details, and keep the police report in your claim file.
How long does an auto claim take to settle?
Claim timing depends on the policy, state rules, the facts of the loss, available documentation, repair availability, and whether liability or value is disputed. Ask the insurer what it still needs and when it expects to update you; do not rely on a standard timeline.
Can I choose my own repair shop?
In most states, the policyholder picks the shop and the insurer cannot force you into a specific network shop, though carriers will often steer you to a “direct repair” partner for speed. Confirm warranty handling with both the shop and the carrier before approving repairs so you know who stands behind the work.
What is the appraisal clause?
The appraisal clause is a contractual mechanism for resolving valuation disputes — most often on total losses — where each side picks an independent appraiser and the two appraisers select an umpire who breaks any tie. If your policy includes it and negotiation on actual cash value has stalled, invoking appraisal can move the dispute forward without immediately going to court.
Next steps
Ask for a written estimate and keep a claims file with all communications.
Sources
- National Association of Insurance Commissioners, “How to File a Complaint and Research Complaints Against Insurance Carriers”
- Insurance Information Institute, “Understanding Your Insurance Policy”
- National Association of Insurance Commissioners, “Auto Insurance”
- National Highway Traffic Safety Administration, “After a Crash”